Beginner Investing Mistakes to Avoid: A Mumbai Financial Guide
Living in Mumbai comes with steep living costs and relentless financial noise. Learn the critical beginner investing mistakes to avoid to build genuine long-term wealth.
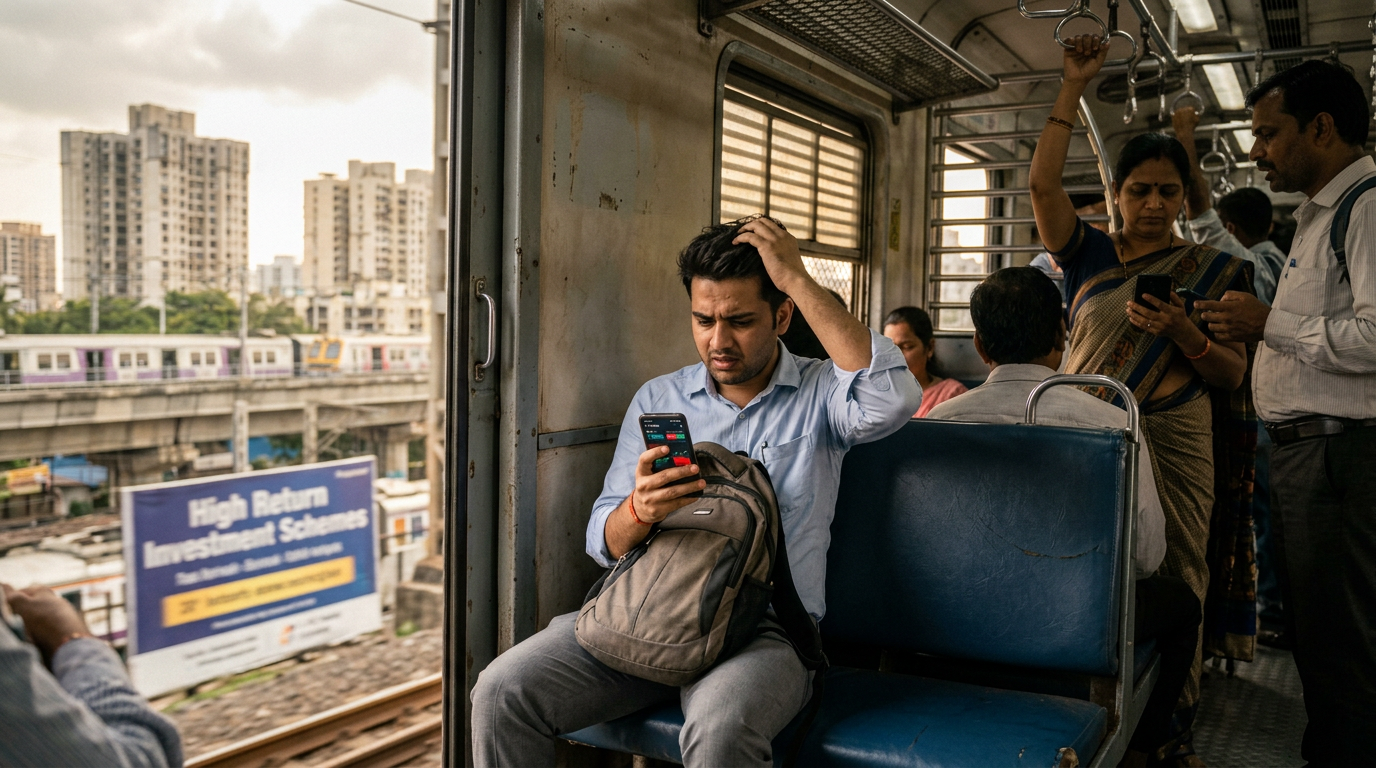
Catch an 8:42 AM fast local from Borivali to Churchgate or grab a table at a cafe in Bandra Kurla Complex (BKC), and you will overhear intense chatter about intraday calls, quick-turnaround IPO flips, and suburban property deals. Mumbai breathes finance. With the Bombay Stock Exchange (BSE) towering over Dalal Street and the National Stock Exchange (NSE) anchored in BKC, capital markets are part of the city's pulse. However, living at the epicenter of financial ambition often pushes novices into hasty decisions. Identifying the primary beginner investing mistakes to avoid is essential if you want your hard-earned money to compound instead of vaporizing under market volatility and high metropolitan living costs.
1. Treating Futures and Options (F&O) Like a Quick Monthly Salary
One of the most dangerous traps catching young professionals across Mumbai, from IT hubs in Airoli to media agencies in Lower Parel, is the siren song of derivatives trading. When monthly expenses for rent, dining out in Powai, and daily travel start eating into income, the promise of doubling capital in an afternoon through index options seems irresistible. Social media feeds are flooded with screenshots of ₹50,000 intraday gains posted by so-called market gurus operating out of high-rises in Andheri.
The reality is stark. Data published by the Securities and Exchange Board of India (SEBI) revealed that nine out of ten individual traders in the equity F&O segment incurred net losses, with the average loss exceeding ₹1.1 lakh per person when factoring in transaction costs. For a beginner, options and futures are not investment vehicles; they are leveraged hedging instruments designed for institutional players and seasoned market makers.
When you place speculative trades without understanding implied volatility, theta decay, or risk-to-reward ratios, you are not investing—you are gambling against algorithms. Before touching complex instruments, build a strong foundation with boring, reliable assets.
"Derivatives are financial weapons of mass destruction for unprepared retail accounts. Real wealth in Dalal Street has always been built on patience, not morning option gambles."
2. Skipping an Emergency Fund in a High-Expense Metro
Mumbai and Navi Mumbai feature some of the highest overhead costs in India. Consider a young couple renting a 1BHK in Vashi for ₹28,000 or a 2BHK in Goregaon East for ₹55,000. When monthly fixed obligations—rent, maintenance, grocery bills, and local transit—run high, pouring every spare rupee into equity markets is a recipe for financial distress.
A classic error among novice investors is running a zero-cash balance. When an unexpected medical emergency strikes, or when an employer in Malad downsizes, an investor without cash reserves is forced to sell equity holdings. If this occurs during a broader market drawdown, they end up liquidating portfolios at a steep loss, permanently locking in capital destruction.
How to Structure an MMR Emergency Reserve
- Calculate True Living Costs: Factor in rent, society maintenance, EMIs, children's school fees, and basic living expenses.
- Target 6 to 9 Months of Runway: In an expensive metropolitan market, aim for at least six months of living expenses safely stashed away.
- Keep It Accessible: Park these funds in a high-interest savings account, short-term fixed deposits with major scheduled banks, or top-rated liquid mutual funds—not in equities or speculative schemes.
Securing this cushion ensures that your long-term equity SIPs remain untouched, regardless of personal or macroeconomic storms. For deeper insights on building stability first, explore our guide to [INTERNAL_LINK: personal finance budgeting in Mumbai].
3. Rushing into Illiquid Suburban Real Estate Too Early
Mumbaikars carry an emotional attachment to real estate. Family elders in Thane or Dombivli often urge 25-year-old professionals to "stop wasting money on rent" and immediately buy a flat. Consequently, beginners jump into under-construction projects in Ulwe, Kharghar, or Mira Road, committing themselves to 25-year home loans.
Buying property prematurely often drains liquid liquidity, locks up cash flow, and restricts geographic mobility. Consider the structural costs associated with purchasing property across the Mumbai Metropolitan Region (MMR):
- High Opportunity Cost: A down payment of ₹15 lakh to ₹25 lakh plus stamp duty (6% to 7% in Maharashtra) completely wipes out the initial capital pool that could have compounded inside diversified equity indices.
- EMI Burden: An EMI of ₹50,000 on a entry-level salary leaves zero room for monthly SIPs, health insurance premiums, or skill development.
- Low Rental Yields: Gross rental yields in Mumbai rarely exceed 2.5% to 3.5%, meaning the property yields poor cash flow relative to its carrying cost and borrowing interest rate.
- Illiquidity: Liquidating a flat during a personal crunch can take anywhere from six months to two years, often forcing distress discounts.
Real estate has its place in a mature, multi-asset portfolio, but treating a leveraged suburban flat as your very first investment asset is one of the biggest beginner investing mistakes to avoid.
4. Following WhatsApp Tips and Social Media "Finfluencers"
Walk into any local Irani cafe near Fort or a workspace in Powai, and you will see people discussing hot stock picks forwarded on messaging apps. Novice investors frequently assume that someone with a large follower count on Instagram or a private channel on Telegram holds exclusive insights into micro-cap gems.
Pump-and-dump operations regularly target retail beginners. Unscrupulous operators buy large positions in illiquid small-cap stocks, spread rumors about massive government contracts or impending buyouts through messaging platforms, and dump their shares onto eager retail buyers once the price spikes. By the time a novice notices the drop, trading volumes vanish, leaving them holding unsellable, devalued scrips.
Red Flags to Watch For
- Guaranteed daily or weekly returns on stock recommendations.
- Pressure to act immediately on "exclusive insider information."
- Advice from unregistered entities lacking SEBI Research Analyst (RA) credentials.
- Screenshots showing massive profits without verified trading account audits.
Genuine wealth creation requires thorough fundamental research or straightforward low-cost indexing, not unverified tips picked up on the evening commute from Belapur to CST.
5. Mixing Life Insurance with Investment Returns
Almost every young earner in Mumbai has experienced this scenario: a friendly family acquaintance or bank relationship manager suggests an endowment policy or a Unit Linked Insurance Plan (ULIP) that promises both life cover and tax-free returns. Eager to satisfy Section 80C tax deductions before March 31st, beginners sign up without scrutinizing policy terms.
Combining insurance and investments invariably results in substandard insurance and underwhelming investments. Traditional endowment policies frequently generate internal rates of return (IRR) hovering around 4% to 5.5%. Given real inflation rates in metropolitan areas—where healthcare, quality schooling, and lifestyle costs expand at 7% to 9% annually—these policies quietly erode purchasing power over a 15-year horizon.
The remedy is simple: unbundle the two needs. Secure a pure, plain-vanilla term insurance plan that provides a life cover equal to 15 to 20 times your annual income at a modest annual premium. Then, direct the remaining funds into transparent, low-expense investment tools like equity mutual funds, Public Provident Fund (PPF), and the National Pension System (NPS). Check out our walkthrough on [INTERNAL_LINK: mutual fund investing for beginners] to understand clear asset division.
6. Mismanaging Gold: Physical Ornaments vs. Sovereign Gold Bonds
Gold holds cultural significance throughout Maharashtra, especially around Gudi Padwa and Dhanteras. Families flock to Zaveri Bazaar in South Mumbai or local showrooms in Dadar to purchase heavy gold jewelry, viewing these purchases as foundational investments.
While gold serves as a dependable hedge against currency depreciation, acquiring physical jewelry as an investment vehicle is highly inefficient due to structural leaks:
- Making Charges: Jewelers charge between 10% and 25% in non-recoverable making and design fees.
- Purity Discrepancies and Storage: Storing physical gold requires bank lockers, which carry annual rental fees and limited availability across branches in Mumbai suburbs.
- GST Drag: Buyers pay an upfront 3% Goods and Services Tax on physical gold that cannot be reclaimed upon resale.
If you want gold exposure in your asset allocation model (ideally 5% to 10% of your total net worth), choose paper or digital formats. Look into Sovereign Gold Bonds (SGBs) traded on secondary exchanges, Gold Exchange Traded Funds (ETFs), or Gold Mutual Funds. These instruments mirror market gold rates accurately without making charges, locker expenses, or purity disputes.
7. Attempting to Time Dalal Street Swings
Every market correction tempts beginners into market timing. When the Nifty slips 500 points on global cues, novice investors pause their monthly Systematic Investment Plans (SIPs), waiting for the market to "bottom out." Conversely, when markets reach fresh all-time highs, they pour lump sums in out of fear of missing out (FOMO).
Professional institutional fund managers with dedicated research desks struggle to consistently time market peaks and troughs; retail investors have virtually zero statistical chance of doing so repeatedly. By stopping an automated SIP during market dips, you miss out on accumulating units at lower Net Asset Values (NAVs)—the exact mechanism that makes rupee cost averaging effective over market cycles.
The Practical Discipline of automated SIPs
Set up an automated bank mandate for your mutual fund SIPs between the 1st and 7th of every month, immediately following salary credits. Treat this allocation as a non-negotiable expense, just like rent or electricity bills. Whether the headline index is up or down, consistency over an 8- to 12-year window smooths out volatility and drives compounding.
8. Constructing a Resilient Investment Portfolio in the MMR Region
Avoiding these common financial missteps requires an organized framework tailored to the financial dynamics of the Mumbai Metropolitan Region. Rather than chasing disparate financial products, assemble a structured, step-by-step portfolio blueprint:
- Secure Base Protection: Purchase comprehensive standalone health insurance (minimum ₹10 lakh to ₹25 lakh base cover with a super top-up) to protect against private hospital bills in Mumbai. Back this with an adequate pure term life insurance policy.
- Build Your Emergency Buffer: Keep 6 to 9 months of living costs split between an auto-sweep bank account and a low-volatility liquid mutual fund.
- Deploy Broad-Market Equity Indexing: Allocate the core of your long-term capital into broad-market index funds (such as Nifty 50 and Nifty Next 50) and a vetted flexi-cap mutual fund.
- Add Debt Stability: Maintain steady contributions to Employee Provident Fund (EPF) or Public Provident Fund (PPF) to anchor the fixed-income portion of your net worth.
- Automate and Review Annually: Let automated mandates do the heavy lifting throughout the year. Review your asset allocation once every twelve months rather than monitoring daily portfolio swings on your phone screen.
Take Control of Your Financial Journey
Building wealth while living in an expensive, fast-moving metropolis like Mumbai does not require insider connections on Dalal Street or speculative day trading. It requires avoiding structural errors that quietly drain your earnings. By establishing an emergency fund, ignoring speculative options bets, resisting social pressure to over-leverage on suburban real estate, and maintaining disciplined, low-cost mutual fund SIPs, you place yourself far ahead of the crowd.
Take an hour this weekend to audit your current bank statements and investment holdings. Weed out high-cost endowment plans, halt speculative trading accounts, and set up automated, sensible investments that will compound peacefully while you live your life. Start small, stay disciplined, and let time work in your favor.
Keep reading
7 Beginner Investing Mistakes to Avoid in Mumbai and Navi Mumbai
Living in Mumbai or Navi Mumbai comes with steep costs and big ambitions. Avoid these critical beginner investing mistakes to protect your capital and grow lasting wealth.
How to Save Money on Groceries: A Realistic Mumbai and Navi Mumbai Guide
Tired of soaring monthly ration bills in MMR? Here is an insider guide to cutting your food expenses across Mumbai, Thane, and Navi Mumbai without sacrificing quality.
Best High Yield Savings Accounts in Mumbai (2024 Guide)
In a city as expensive as Mumbai, your savings need to work harder. Discover the best high-yield savings accounts that offer up to 7.5% interest, far outpacing traditional banks.