7 Beginner Investing Mistakes Every Mumbaiite Must Avoid
New to investing in Mumbai? This guide breaks down the critical beginner investing mistakes to avoid, from FOMO on hot stocks to underestimating real estate in Thane or Panvel.
A Beginner's Guide to Investing in Mumbai: Don't Make These Mistakes
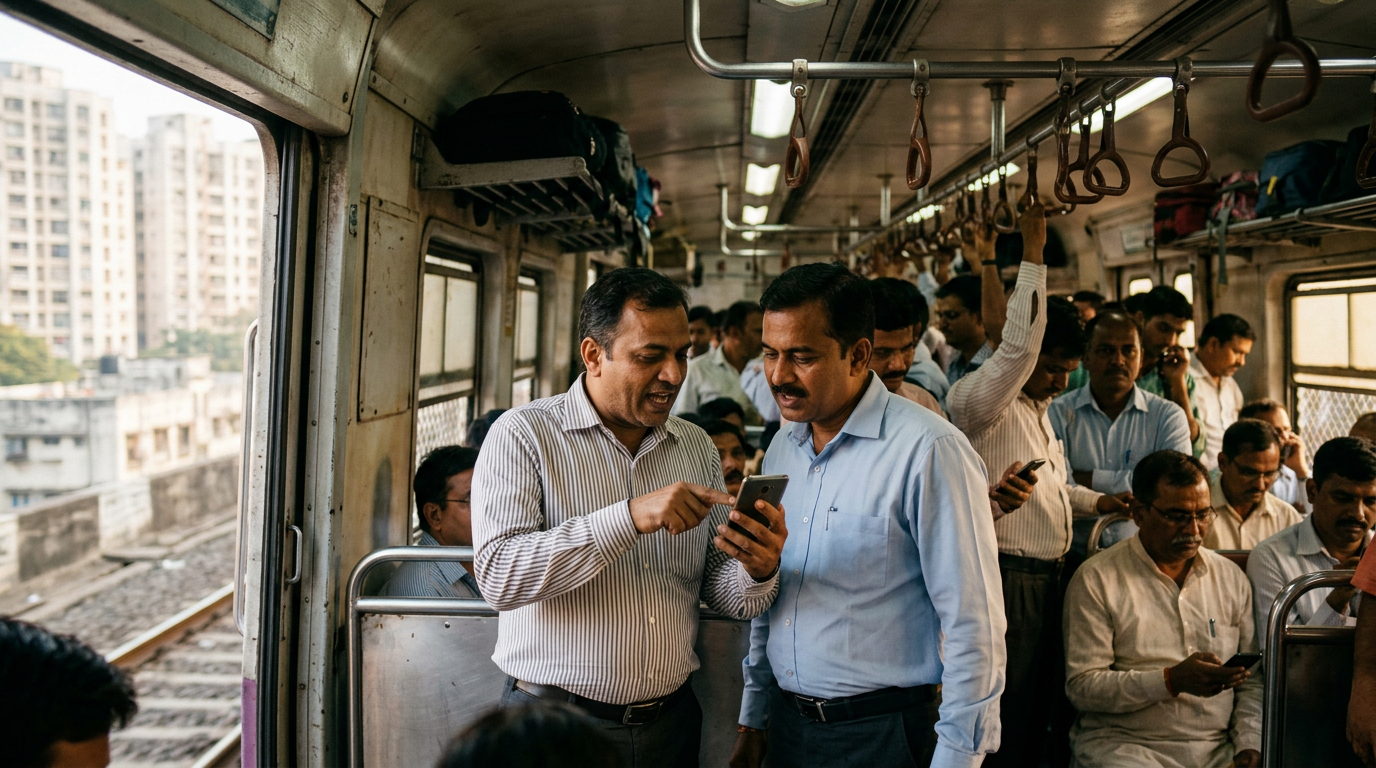
The 7:42 AM Virar fast is pulling into Andheri. It’s packed, as always. Amidst the daily chatter, you overhear two people talking animatedly about a 'sure-shot' stock that’s going to double in a month. The temptation is real. In a city that runs on ambition, where fortunes are made and lost with dizzying speed, the urge to jump on the investment bandwagon is immense. But this energy can also lead to classic beginner investing mistakes that can derail your financial goals before you even leave the station. This guide isn't about hot tips; it's about building a solid foundation to grow your wealth, whether you're in a Bandra high-rise or a quiet lane in Nerul.
Mistake #1: Listening to 'Hot Tips' from the Local Train Network
In Mumbai, information travels faster than the monsoon floods. From the office canteen in BKC to the WhatsApp group for your Kandivali housing society, everyone seems to have a stock tip. A friend’s cousin’s colleague in an investment bank supposedly has insider info. While it’s tempting to act on these whispers, this is one of the most dangerous traps for a new investor. These tips are often just noise. They lack context, research, and an understanding of your personal financial situation. The person sharing the tip about a small-cap pharma stock might have a massive risk appetite, while you’re saving for a down payment on a flat in Thane.
Think of it this way: investing based on a tip is like deciding to buy a property in Panvel solely because someone on the Harbour Line said prices are “about to explode.” You would never do that without visiting the site, checking the paperwork, and assessing the infrastructure. Your stock investments deserve the same, if not more, diligence. Most of these tips are part of a 'pump and dump' scheme or are based on lagging information. By the time the news reaches your local train compartment, the smart money has already moved on. The foundation of good investing is research and analysis, not rumour and speculation heard over the clatter of the tracks.
Mistake #2: The Classic Mumbai FOMO (Fear of Missing Out)
Mumbai thrives on a competitive spirit. You see it in the queues for college admissions, the hustle for promotions, and the race for the last seat on the 6:15 PM CSMT local. This translates directly into investing. When your colleague in Powai talks about their crypto portfolio multiplying, or a relative in Juhu mentions a 'multi-bagger' stock they bought, the Fear of Missing Out kicks in hard. This leads to chasing performance—piling into an asset only after it has seen a significant price surge. This is the financial equivalent of trying to get into a popular SoBo restaurant on a Saturday night without a reservation; you'll likely be late and overpay.
Don't Chase; Plan
FOMO-driven investing is reactive, not strategic. Remember the frenzy around certain stocks during 2021? Many who jumped in at the peak, driven by social media hype and success stories, saw their capital erode just as quickly. A disciplined investor with a plan would have assessed if that stock fit their long-term goals and valuation criteria, rather than buying out of pure social pressure. Your friend's success with a risky asset doesn't mean it's the right choice for you. Your journey is unique. Building a portfolio based on your own goals—be it funding a child's education or retiring early to a home in Lonavala—is the only sustainable path. Let others chase the trends; you focus on your plan.
Mistake #3: All Eggs in One Basket (Especially the Real Estate Basket)
For generations of Mumbaikars, the ultimate financial security was owning property. The dream of buying a 1BHK, then upgrading to a 2BHK in a good neighbourhood like Vile Parle or Chembur, has been the primary investment goal. While owning your own home is a valid aspiration, considering real estate as your only investment is a massive diversification failure. The Mumbai property market, while resilient, can also stagnate for years. Moreover, it is incredibly illiquid. If you need to raise cash urgently for a medical emergency, you can’t just sell one bedroom of your Borivali flat. The process of selling property is long, cumbersome, and expensive.
True wealth creation comes from diversification. A healthy portfolio spreads risk across different asset classes that don't all move in the same direction. A well-diversified starter portfolio for a Mumbai-based professional might look something like this:
- Indian Equities: For long-term growth. Start with Nifty 50 or Sensex index funds to buy a piece of India's top companies.
- Debt Instruments: For stability and fixed returns. Think Public Provident Fund (PPF), high-quality corporate bonds, or even traditional Fixed Deposits for short-term goals.
- Gold: As a hedge against inflation and market uncertainty. Sovereign Gold Bonds (SGBs) are a tax-efficient way to invest.
- Real Estate (Alternative): Instead of locking up crores in a single property, consider Real Estate Investment Trusts (REITs). They allow you to invest in a portfolio of income-generating commercial properties (like office parks in Airoli or malls in Lower Parel) with a much smaller ticket size and high liquidity. [INTERNAL_LINK: what are reits and how to invest]
Mistake #4: Ignoring the Growth Story in Navi Mumbai and the Extended MMR
There's a certain glamour to investing in companies headquartered between Nariman Point and Bandra-Kurla Complex. Many new investors are drawn to legacy brands and businesses that dominate the island city's landscape. In doing so, they completely miss the massive economic engine roaring to life across the Thane Creek. The future growth of the Mumbai Metropolitan Region (MMR) is inextricably linked to Navi Mumbai, Thane, Panvel, and beyond. The development of the Navi Mumbai International Airport, the Mumbai Trans Harbour Sea Link, and countless infrastructure projects is creating a new economic nexus.
"An intelligent investor in Mumbai today doesn't just look at the established players in South Mumbai. They look at the logistics companies benefiting from the JNPT port, the real estate developers building new townships in Kharghar and Ulwe, and the consumption-driven companies that will cater to the millions moving into these new growth corridors."
Don't be myopic. Broaden your research. Which engineering firm has a major contract for the new metro line? Which retail chains are aggressively expanding into Thane and Kalyan? Investing in these themes is how you capture the next wave of growth, rather than just riding the coattails of the last one. The opportunities are not just in the high-rises you see from Marine Drive, but also in the new frontiers being built across the entire MMR.
Mistake #5: Underestimating the Silent Killers: Fees and Taxes
You're thrilled. Your mutual fund statement shows a 15% annual return. But what you actually get in hand can be significantly less, thanks to a host of fees and taxes that slowly eat away at your wealth. For a beginner, these costs are often hidden in the fine print and easy to overlook. A fancy wealth manager with an office in Lower Parel might promise great returns but charge a 2% annual fee, which is a huge drag on your portfolio over time. Even seemingly small differences in costs can have a massive impact over decades due to the power of compounding.
Know Your Costs
Before you invest a single rupee, make sure you understand the cost structure:
- Expense Ratio (for Mutual Funds): This is an annual fee charged by the fund house. Always, always opt for 'Direct Plans' over 'Regular Plans'. Direct plans have a lower expense ratio because they cut out the distributor's commission. The difference might look small (e.g., 0.5% vs 1.5%), but over 20-30 years, it can amount to lakhs of rupees. [INTERNAL_LINK: understanding mutual fund direct vs regular plans]
- Brokerage Fees: With the rise of discount brokers like Zerodha, Groww, and Upstox, you should not be paying high brokerage fees for simple equity transactions. Traditional full-service brokers may be suitable for high-net-worth individuals needing advisory, but for a beginner, low cost is key.
- Taxes: The government wants its share. Understand the basics of Short-Term Capital Gains (STCG) and Long-Term Capital Gains (LTCG) on equities and mutual funds. Knowing the tax implications can influence your decision to hold an investment for more than a year to qualify for lower LTCG tax rates.
Mistake #6: Investing Without a 'Why' – Lacking Clear Financial Goals
Why are you investing? If your answer is a vague "to make money," you're setting yourself up for failure. Investing without a clear goal is like boarding a train at Churchgate with no destination in mind. You'll end up getting off at a random station, or worse, panicking and jumping off when the train speeds up or slows down unexpectedly. Your financial goals determine your investment horizon, risk tolerance, and the right products for you. Without this North Star, you are susceptible to making emotional decisions, like panic-selling your entire portfolio during a market correction.
Get specific. Instead of "saving for the future," define what that future looks like. Here are some concrete examples for a Mumbaikar:
- Short-Term (1-3 years): Saving ₹5 lakhs for a wedding. Strategy: Low-risk debt instruments like FDs or liquid funds. Equity is too volatile for this timeframe.
- Mid-Term (5-7 years): Accumulating a ₹20 lakh down payment for a 2BHK in Airoli. Strategy: A balanced approach. Perhaps a 60/40 split between equity mutual funds and debt funds.
- Long-Term (15+ years): Building a retirement corpus of ₹3 crores. Strategy: An aggressive, equity-heavy portfolio (80%+ in equities), taking advantage of the long time horizon to ride out market volatility.
Once you attach a 'why' to your money, it becomes easier to stay disciplined and ignore the market noise. [INTERNAL_LINK: how to set smart financial goals]
Mistake #7: Trying to Time the Market
This is the holy grail for novice investors and the biggest mistake of all. They believe they can outsmart the collective wisdom of the market. They'll wait for the "perfect" time to buy ("I'll invest when the Sensex drops to 50,000") or try to sell at the absolute peak. The reality is, not even the most seasoned traders on Dalal Street can consistently time the market. It's a fool's errand. Research has shown that a vast majority of long-term returns come from just a handful of the best trading days. If you're sitting on the sidelines in cash, waiting for the perfect entry point, you are very likely to miss those days.
The solution is beautifully simple: Time in the market beats timing the market. The most powerful tool for a beginner investor is the Systematic Investment Plan (SIP). An SIP is like an EMI for your investments. You commit to investing a fixed amount (as little as ₹500) every month in a chosen mutual fund. When the market is high, your fixed amount buys fewer units. When the market is low, it buys more units. This process, called rupee cost averaging, smooths out your purchase price over time and removes the need to guess the market's direction. It instills discipline and automates the process of wealth creation, just like a scheduled bill payment. It's the single most effective way to turn the market's volatility into your friend.
Your Journey Starts Now
The journey to financial independence in a city as expensive as Mumbai can feel daunting. But it's not about making a million overnight. It's about starting, staying disciplined, and avoiding these fundamental errors. Don't listen to tips on the train, don't give in to FOMO, diversify beyond that dream flat in Dadar, look for growth across the MMR, mind the fees, define your goals, and for heaven's sake, don't try to time the market. Your financial future is a marathon, not a sprint down the Marine Drive promenade. The best time to start was yesterday. The next best time is now.
Ready to take the first, most important step? Read our simple guide on [INTERNAL_LINK: how to start an SIP in India] and put your money to work the smart way.
Keep reading
7 Beginner Investing Mistakes Every Mumbaikar Must Avoid
From the Dalal Street buzz to property chatter in Panvel, starting your investment journey in Mumbai is exciting. Avoid these common beginner investing mistakes to build wealth.
How to Save Money on Groceries: The Ultimate Mumbai Guide
Feeling the pinch from rising food costs? Our ultimate Mumbai guide reveals practical tips on how to save money on groceries, from mastering wholesale markets to decoding app discounts.
Cut Your Grocery Bill: A Mumbaikar's Guide to Saving Money
From the crowded markets of Dadar to the aisles of DMart in Panvel, grocery costs are rising. This guide offers practical, Mumbai-specific strategies to save money on groceries.